Damaged a Neighbour's Property During Building Work?
The short answer
If your work has damaged a neighbour's property, make it safe, photograph everything, tell the neighbour and your client the same day, and notify your public liability insurer before you admit fault or promise to pay. Who pays depends on whether you were negligent, what your contract says and whether party wall notices were served. Most of it is preventable with a dated schedule of condition before you start.
- First 24 hours. Make safe, photos and video, write down what happened, tell the neighbour and the client.
- Insurer before promises. Notify your public liability insurer within the policy time and don't admit fault first.
- Who pays depends. Your negligence, your contract with the client and the Party Wall Act all play a part.
- Prevent it. Dated condition photos of next door, party wall notices checked before you dig, protection planned.
Damaged a neighbour's property during building work? A crack has opened in next door's wall after you dug the footings. Or a skip lorry clipped their car, or water from your strip-out came through their ceiling. The neighbour is at the door, your client is on the phone, and you are wondering who pays and what to say.
This guide is for UK building company owners in that spot. It covers the first 24 hours, your insurer, the Party Wall Act and who usually pays. Then how to stop it on the next job.
It comes from the owner of a working London construction company that builds in tight terraced streets. If you want to talk your situation through, book a free strategy call.
Damaged property during building work: the first 24 hours
What you do on day one decides most of what happens next. Keep it calm and keep it on paper.
- Make it safe: stop the work that caused it, prop or cover if needed, and keep people away.
- Record everything: photos and video of the damage and your work next to it, with the date and time.
- Write down what happened: who was working, what they were doing, the weather, any witnesses.
- Tell the neighbour and your client: the same day, politely, with what you are doing next.
- Tell your insurer or broker: today if you can, and always within the time your policy gives.
Be kind to the neighbour. Say you are sorry it happened and that you will deal with it properly. That is not the same as saying it was your fault.
Promising on the doorstep to "sort it all out" or paying cash to make it go away. You may have just admitted liability and lost your insurance cover for the same damage.
Call your insurer before you promise anything
Damage to a third party's property is what public liability insurance is for. Your policy will have rules, and you need to follow them.
- Report on time: many policies say incidents must be reported as soon as practical, sometimes within a fixed number of days.
- Forward letters fast: any letter or claim from the neighbour or their solicitor goes to the insurer straight away.
- Don't admit fault: most policies don't let you admit liability or agree to pay without their consent.
- Know your excess: the first part of any claim is yours to pay.
Late reporting is not a small detail. In a 2023 case, a public liability policy said incidents must be reported within 30 days. The business reported late, and the court held the insurer could refuse to pay. Read your policy wording today, not after the claim.
Not sure how to handle the neighbour, the client and the insurer at once?
Book a free strategy call and we'll help you plan the next steps.
Who usually pays
There are three parts to the answer: what caused it, the Party Wall Act and your contract with the client.
| Situation | Who usually pays | What to check |
|---|---|---|
| Your team was careless | You, through your public liability insurance | Your policy, excess and the evidence |
| Party wall works caused it | The building owner (your client) must make good, and may look to you | The party wall award and your contract |
| The damage was there before | Nobody for that part | Your dated condition photos |
| A subcontractor caused it | You to the client, then you claim from the sub | Your subcontract and their insurance |
Under the Party Wall etc. Act 1996, the building owner, your client, must make good any damage to next door caused by the notifiable works, or pay compensation. Your client will then usually turn to you. Many building contracts, including JCT, make the contractor cover the client for damage to property caused by the contractor's negligence or default.
So even when the law points at your client first, the bill often comes back to you. That's why your contract and your insurance matter more than who the neighbour shouts at.
Pre-existing damage is the big one. In a 2024 Court of Appeal case, a building owner was not liable for underpinning that fixed old defects his works did not cause. To prove what was there before, you need dated photos from before you started.
This is general information, not legal advice. For a serious claim, speak to your insurer and a construction solicitor.
Party wall notices: never start without them
Serving party wall notices is the client's job, but starting work without them is your risk. The notice periods are:
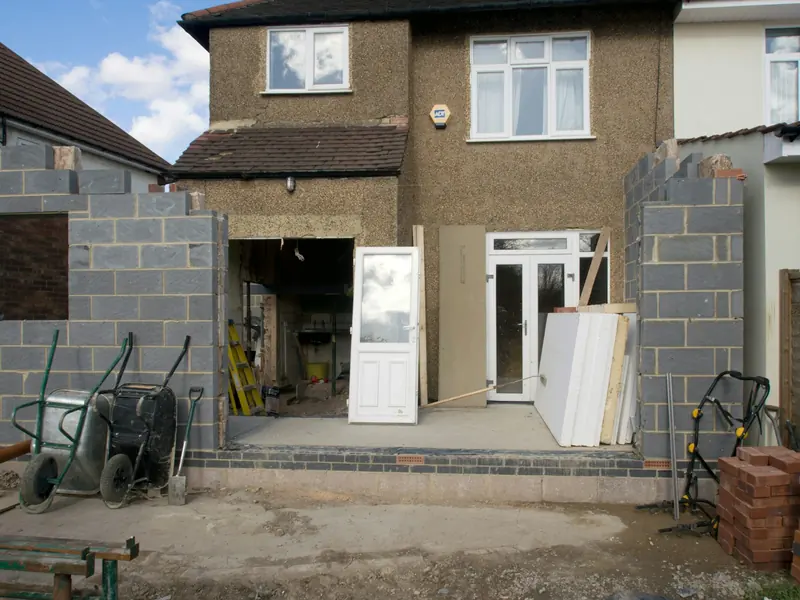
Digging within 3 or 6 metres of next door's foundations can need notice too, depending on depth. If notices were not served, the neighbour can go to court to stop the work or claim damages. You also lose the agreed record of next door's condition that comes with a party wall award.
Before you start, ask your client for the notices, the neighbour's consent or the award. Put it in your contract that you won't start notifiable work without them. Sviat advises bespoke contracts for private clients for exactly this reason: they protect the builder, not just the client. See JCT vs a bespoke building contract.
Stop it happening on the next job
Most neighbour claims can be prevented or defended with a few habits:
- Condition photos before you start: dated photos and video of next door's walls, ceilings, drive and car park side, shared with the neighbour.
- Party wall papers checked: no dig, no cut into a party wall, until you have them.
- Protection planned: propping, dust and water protection, and where the skip and deliveries go.
- Daily site report with photos: the record of what you did each day, in case a claim comes months later.
- Subcontractors with insurance: see a copy of their public liability policy before they start. More in how to find reliable subcontractors.
- Insurance that fits the job: check your cover limit against what the job could damage, and what your client or main contractor asks for.
These come from the systems Sviat uses to run Craftex. Every job has a start meeting, a daily site report with photos and a handover pack. If ground conditions surprise you, read unforeseen works: who pays.
Worried this claim will eat your profit?
Book a free call with our team. We'll help you handle this one calmly and set up jobs so it doesn't happen again.
Run jobs that protect your profit
Oleg started as a taper on London sites. He moved from doing the work to running the jobs and built a team of 10+ people. He went from £2K to £7K a month profit in 2 months.
Individual results, not typical or guaranteed.
Sviat mentors owners one to one himself, while still running his own construction company.
Every business is different. He looks at how you start and run jobs, your contracts and your team, and builds the systems that fit. The aim is results in about 4 months, not the 1–3 years many coaching programs take.
Want jobs that don't end in claims? Book a free strategy call. Or score your business in 4 minutes with the free Construction Business Scorecard. If you want help putting site rules and contracts in place across every job, see our one-to-one programs.
The Systems Blueprint for UK Builders
The start meeting, daily site report with photos and handover pack that protect you when something goes wrong.
Get the free guideBefore you start the next job
- Dated photos and video of next door are taken and shared
- Party wall notices, consent or award are in your file
- Your public liability policy wording and excess are checked
- Every subcontractor's insurance is on file
- Protection, skip and delivery plan is agreed with the client